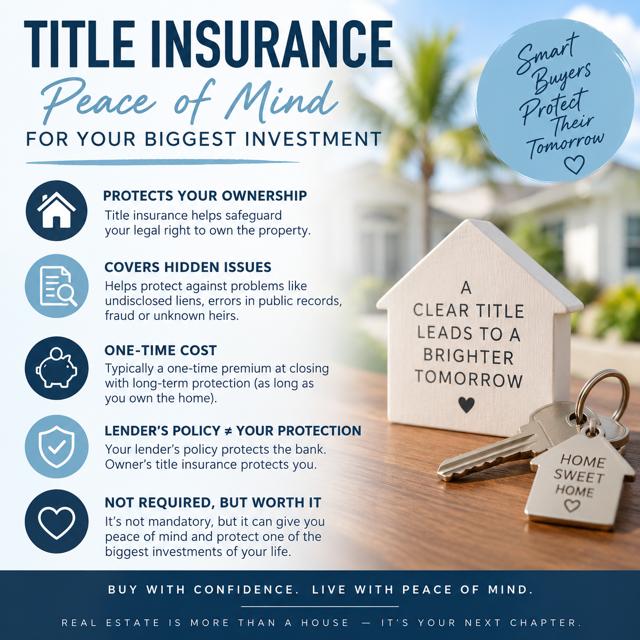
Buying a home involves many expenses, so buyers often question owner’s title insurance, especially when it isn’t required.The simple answer: Title insurance helps protect your ownership of the property.
What Is Title Insurance? When you buy a home, you acquire legal ownership, or “title,” to the property. Before closing, a title company searches public records for liens, claims, errors, and other issues that could affect ownership. Although a thorough search can identify many problems, some defects may remain undiscovered. That’s where title insurance comes in.
What Can Go Wrong With a Property’s Title? After closing, a title issue involving a previous owner could surface. Depending on the policy, covered problems may include:
- Errors or omissions in public records
- Undisclosed liens
- Mistakes in deeds or other recorded documents
- Forged or fraudulent documents
- Missing heirs claiming ownership
- Problems with prior transfers
- Certain boundary, easement, or recording issues
- A claim from someone asserting an ownership interest is an unwelcome surprise for any homeowner.
Lender’s Title Insurance vs. Owner’s Title Insurance If you finance your purchase, your lender will generally require a lender’s title insurance policy. It protects the lender’s financial interest—not your ownership.An owner’s title insurance policy protects your ownership interest, subject to the policy’s terms, exclusions, exceptions, and coverage limits. The lender’s policy protects the lender. The owner’s policy protects you.
Why Buy Owner’s Title Insurance If It Isn’t Required?
“Not required” does not mean “not important.” A home is often one of your largest investments. Owner’s title insurance helps protect that investment against certain covered title defects that existed before you purchased the property but were discovered afterward. The policy is typically purchased with a one-time premium at closing and generally remains in effect while you retain an insured interest in the property, subject to its terms. If a covered claim arises, the policy may provide legal defense and payment of covered losses up to the policy limits.
Isn’t the Title Search Enough? A title search helps identify and correct known problems before closing, but it cannot guarantee that every defect will be found. Some issues may not appear in public records or may result from fraud, recording errors, or incorrect documents. Title insurance protects against certain covered problems that were not discovered before closing. The search and the insurance serve different purposes—and both can matter.
Is It Worth the Cost? Every buyer should review the property, transaction, policy, cost, and personal tolerance for risk. However, a one-time closing expense may help protect hundreds of thousands of dollars in home equity and ownership rights. Before declining coverage, ask the title or closing professional:
- What does the policy cover?
- What exclusions and exceptions apply?
- How long does coverage last?
- What happens if a title problem appears after closing?
You worked hard to buy your home. Protecting your right to own it deserves careful consideration.
Note: This article is for general informational purposes only and is not legal, title, or insurance advice. Requirements, coverage, practices, and costs vary by location and transaction. Review your policy and consult the appropriate title, closing, insurance, or legal professional with questions about your circumstances.